

Best Brokers With Individual Savings Accounts (ISAs) 2026
Discover our top brokers offering Stocks and Shares Individual Savings Accounts, or ISAs, selected after rigorous testing for their tax-efficient investment options.
 Written By
Royston Wild
Royston is a seasoned investor and financial writer with over a decade of experience analyzing brokers and investment markets. With a background in stocks, commodities, and forex reporting - he brings a fresh perspective to broker evaluations.
Royston Wild Profile Page Fact Checked By
Tobias Robinson
Tobias is committed to helping traders find the right brokerage for their needs. He has tested 200+ brokers, spent 2,600+ hours using different platforms, and placed 2,100+ trades.
Tobias Robinson Profile Page Edited By
James Barra
James is an experienced broker analyst with a background in financial services. He has spent 2,500+ hours testing brokers, used 35+ different platforms and apps, audited 120+ broker T&Cs, and verified 300+ regulatory licenses. James has also been on US and UK TV, and been a guest on finance podcasts, discussing reports conducted by BrokerListings.com and sharing his expertise.
James Barra Profile PageAugust 2, 2026
Filters
How We Chose the Best ISA Brokers
To determine the best brokers for ISAs, we used a data-driven approach that combines comprehensive analysis and hands-on testing:
- 200+ Metrics Assessed – We evaluated each provider based on key factors such as ISA availability, fees, platforms, customer service, and regulatory standing.
- Hands-On Testing – Our British testers, several of whom have ISAs themselves, conducted real-world assessments of each platform to gauge ease of use, reliability, and overall experience.
What to Consider When Searching for A Top Stocks and Shares ISA Provider
We’ve done the digging and know not all ISA providers offer the same quality of service. Here are the key things to think about when selecting a product provider:
Regulatory Status
The first thing to check is that the broker you’re considering is licensed to trade by the Financial Conduct Authority (FCA). To offer an ISA, a company must be approved by the UK regulator as well as HM Revenue & Customs (HMRC).
Pro tip: Check a broker’s regulatory status on the FCA’s online Financial Services Register.
Rapid growth in financial services fraud makes checks like this essential. But as well as protecting one’s money and valuable financial data, it can also help individuals avoid businesses with poor business practices.
For example, CMC Markets continues to earn its status as one of our most trusted ISA providers with authorization from the FCA and a listing on the London Stock Exchange, ensuring financial transparency.
Product Range
Stocks and Shares ISAs allow individuals to trade across four major asset classes: equities, trusts, funds and bonds. But the range of financial securities a broker offers within these categories can vary significantly.
For example, interactive investor offers one of the widest product selections out there. Traders can buy and sell thousands of shares listed in 17 international locations, for instance, while its catalogue of 3,000-plus funds is one of the largest on the market.
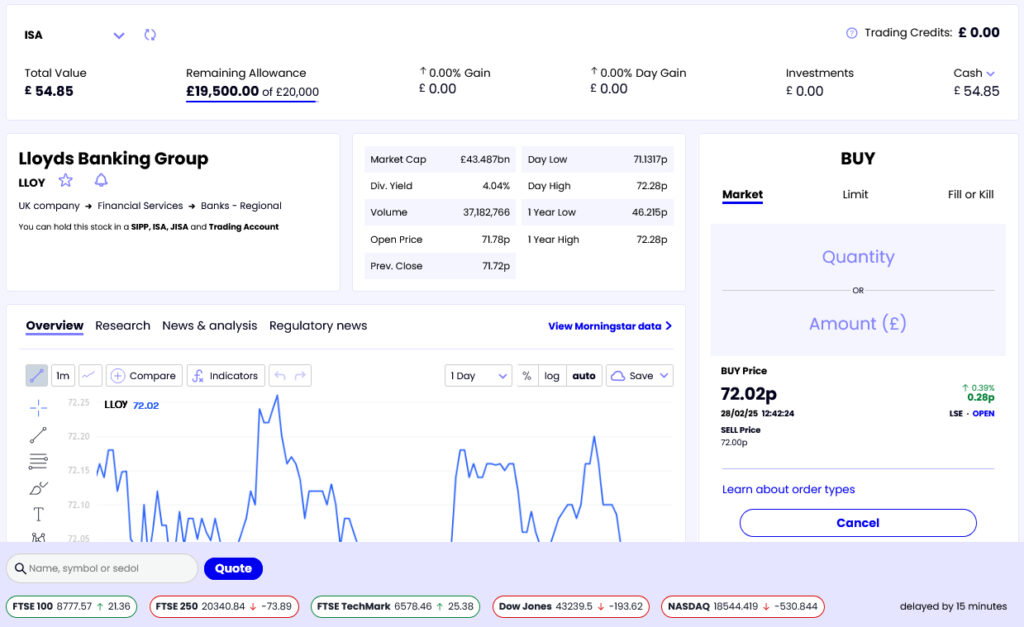
interactive investor has a user-friendly platform for managing ISA investments
Type of Stocks & Shares ISA
The number of banks, building societies, brokerages and other financial institutions offering these tax-efficient products is vast.
However, the range of those offering the more versatile Flexible Stocks and Shares ISA is much more limited.
If you’re thinking about making regular withdrawals, you should seriously consider opening a flexible product.
For example, IG is one of the top companies offering these niche accounts.
Fees
These can differ substantially across brokers, so investors should check charge tables carefully.
Many providers offer reduced commissions for frequent traders or those with high account balances. So estimate how many trades you expect to make each month – along with your portfolio size – when thinking about provider fees.
With management fees, some providers charge these as a percentage of an individual’s portfolio, while others take payment in the form of a flat fee. Most brokers nowadays don’t charge account setup or withdrawal fees, but investors should be on guard for such costs.
For example, Interactive Brokers is lower-cost than other major players in the market like Hargreaves Lansdown, as IBKR charges no annual platform fee (0%) for stocks, ETFs, and bonds, compared to Hargreaves Lansdown’s annual fee of up to 0.45%.
Trading Platform and Tools
It’s important to consider how user friendly the trading interface is, especially if you’re planning to spend a large period of time placing trades.
Think about ease of navigation, execution speeds, platform tools (like advanced charting) and the general attractiveness of the trading software.
Also consider the type of educational resources and other trading material the financial services provider gives to its customers.
For example, interactive investor operates the ‘ii Community,’ an excellent social network for traders to interact on.
Rewards
The ultra-competitive ISA market means providers are falling over themselves to offer incentives to encourage investors to open an account or switch from another company.
As with current accounts, switching rewards are commonplace. These can often be tiered according to the size of one’s portfolio.
Other rewards include brokers who offer high interest rates on cash. For example, XTB has some of the highest interest rates in the market during our latest tests.
FAQ
What Is a Stocks and Shares ISA?
Introduced in 1999, the ISA suite of products seeks to encourage people to save and invest for the future. The most popular are the Cash ISA and the Stocks and Shares ISA.
Individuals can invest up to £20,000 in these two products in any one tax period. This can be deposited in one type of account or spread across various. For instance, an individual can put £10,000 in a Stocks and Shares ISA and £10,000 in a Cash ISA in a tax year.
Despite its name, the Stocks and Shares ISA doesn’t restrict holders to simply investing in equities. Users can also invest in the bond markets, trade investment trusts, and buy and sell funds (including exchange-traded funds (ETFs)).
Individuals can also purchase these assets in a Lifetime ISA. With these products, investors also receive a £1 government top-up for every £4 they deposit.
However, only individuals under the age of 40 can open a Lifetime ISA, and deposits (up to a maximum of £4,000 per tax year) can only be made up to the age of 50.
Strict withdrawal rules also make these products largely unsuitable for conventional trading. These include slapping a 25% penalty on those pulling money out before they reach 60 years old.
With a standard ISA, any withdrawals that savers and investors make are not returned to their annual allowance for the tax year. Individuals can get around this problem by opening a Flexible ISA, which allows withdrawals to be replaced within the same tax year without affecting the annual ISA allowance.
What Are the Pros of an ISA?
Trading financial securities in an ISA instead of with a General Investment Account (GIA) can have significant advantages:
- Protection from Capital Gains Tax (CGT) and Dividend Tax.
- Returns don’t need to be reported to HM Revenue and Customs (HMRC), making the tax assessment process simpler.
- Investors have a wide range of providers to choose from.
What Are the Cons of an ISA?
There are drawbacks to using one of these tax-efficient products, including:
- Restrictions on annual deposits and withdrawals (in the case of the Lifetime ISA).
- Some asset classes are off-limits, like cryptocurrency and forex.
- ISAs are only available to UK residents.
Article Sources
Individual Savings Accounts (ISAs) – GOV.UK
Financial Services Register – Financial Conduct Authority (FCA)